
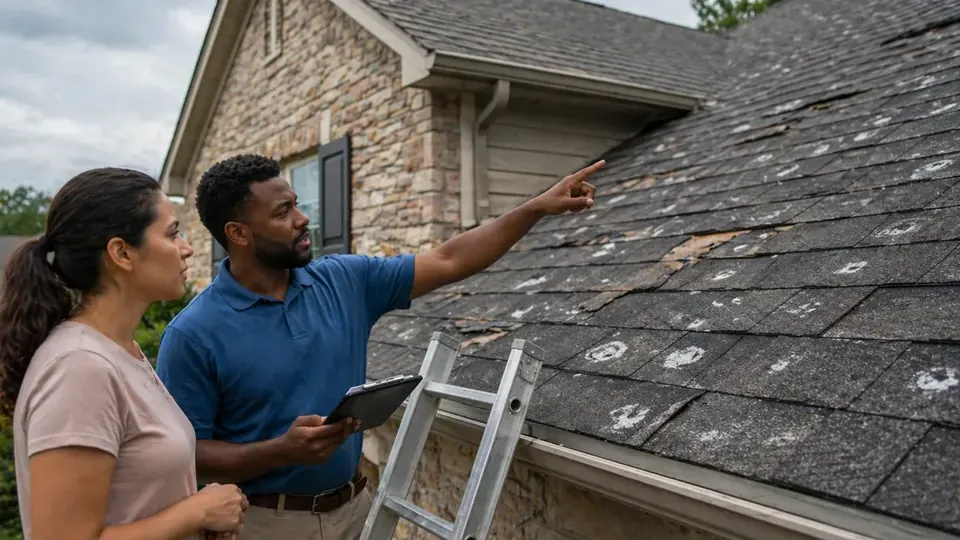
Insurance claim supplements in Corpus Christi are a normal part of many property claims, not a sign that something went wrong. Adjusters write estimates from what they can see on inspection day, often during a catastrophe workload after a major storm. Once a roofer tears off shingles or a contractor opens a wall, more damage may appear. Code requirements, permit costs, and pricing changes may also be missing from the first estimate. A supplement documents those items and asks the insurer to adjust the claim. Corpus Christi Public Adjuster helps property owners prepare supplements that are specific, supported, and easy for the insurer to evaluate.
When a Supplement May Be Appropriate
Common situations include:
- Hidden damage found during repairs, such as deteriorated decking under a hail-damaged roof, wet insulation behind drywall, or water damage under flooring.
- Items missed on inspection, including roof accessories, gutters, fences, detached structures, or entire rooms.
- Code and permit requirements that apply to the repair but were not included.
- Quantity corrections, where measurements or waste factors were too low.
- Price changes between the estimate and the repair, when local costs rose after a storm.
- Matching problems, where repaired areas cannot reasonably match undamaged areas, depending on the policy and facts.
- Additional living expense or business income that ran longer than first expected.
Items Often Missed in Coastal Bend Estimates
Corpus Christi sits inside the TDI windstorm catastrophe area, and local code and certification requirements add line items that first estimates often leave out. The table below lists examples; whether each one is payable depends on your policy, the damage, and the applicable code.
| Item | Why it is often missed | Supporting documentation |
|---|---|---|
| Roof decking replacement | Damage is not visible until shingles are removed | Photos during tear-off, sheet counts, roofer invoice |
| Underlayment, drip edge, starter, ridge | Left off when only shingles are scoped | Manufacturer instructions, code references |
| Windstorm inspection and certification | Treated as outside the repair scope | Engineer or inspector invoice, WPI-1 and WPI-8 documents |
| City permit fees | Not included in default estimates | Permit receipt from the city portal |
| Code-required fastening or materials | Estimate assumes like-for-like replacement | Code section, engineer letter, ordinance or law coverage terms |
| Interior drying and mold-related work | Moisture not measured at first inspection | Moisture maps, drying logs, remediation reports |
| Detached structures and fences | Not inspected or not listed | Photos, measurements, separate line items |
Corpus Christi requires a permit to re-roof, and the city's roofing submission includes a TDI WPI-1 form from the windstorm engineer or inspector. For more on certificates, see our article on WPI-8 windstorm certificates and the local building codes page. The TDI Windstorm Inspection Program explains which work requires inspection.
How to Document a Supplement
- Photograph before it is covered. Take wide shots for location and close-ups for detail, with a tape measure or reference object in frame.
- Notify the insurer in writing as soon as hidden damage is found, and offer a chance to reinspect.
- Write line items, not totals. A supplement that lists each added item, its quantity, and its unit price is easier to approve than a single lump sum.
- Explain why each item belongs. Tie it to the damage, a code section, or manufacturer instructions.
- Attach invoices and receipts for completed work, permits, inspections, and materials.
- Track depreciation. On replacement cost policies, submit proof of completed repairs to recover depreciation within the policy deadline.
- Keep copies of everything sent, with dates.
Our claim documentation checklist and the article on what carriers miss in hail claim scopes give more examples.
Why Supplements Get Rejected
Insurers decline supplements for predictable reasons, and most of them come down to documentation. A supplement may be denied when:
- The added damage was repaired or covered up before the insurer could see it, and the photos do not show it clearly.
- The request lists a lump sum with no line items or quantities.
- The supplement does not explain how the new damage relates to the original covered loss.
- A code-related item is requested without the code section, permit requirement, or policy coverage that supports it.
- The insurer believes the item reflects wear, prior damage, or an upgrade rather than restoration to pre-loss condition.
- The request arrives after a policy deadline, such as the time allowed to complete repairs and recover depreciation.
Each of these can often be avoided with timely notice and clear support. When a supplement is rejected, ask for the reason in writing. A Corpus Christi Public Adjuster can review the response and help you decide whether additional evidence, a reinspection, or another step makes sense.
Reopening a Previously Settled Claim
Many property owners assume that once a check is issued, the claim is over. Often it is not. Depending on the policy and timing, a claim may be reopened when additional damage surfaces later, when repairs reveal hidden issues, when the original pricing or scope was incomplete, or when the payment did not reflect the real cost of repair. Read any release or settlement document carefully, and if you are unsure of its legal effect, consult a Texas attorney.
For TWIA windstorm claims, keep the statutory timeline in mind: a claim must be filed no later than one year after the date of damage, with a possible extension of up to 180 days for good cause, and amount disputes go through appraisal deadlines that start when TWIA issues its acceptance notice. Use the claim deadline calculator to estimate those dates.
How We Help With Supplements
We review the insurer's estimate line by line, inspect the property (including during tear-off or demolition when timing allows), and prepare a supplement in Xactimate with photos and explanations for each item. We submit it, respond to the insurer's questions, and follow up through reinspection. If the insurer and policyholder agree on coverage but cannot agree on the amount, we can explain how insurance appraisal works and whether it may fit.
A supplement is a request, not a guarantee. Some items will be approved, and some may not be, depending on the policy and the evidence. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. For a second look at your paid claim, start with an insurance estimate review or request a Free Claim Review.
Frequently Asked Questions
What is an insurance claim supplement?
A supplement is a request for additional payment on an existing claim. It covers damage, materials, or costs that were not in the insurer's original estimate, such as hidden damage found during repairs or items the adjuster missed.
Is there a deadline to submit a supplement?
Policies often set time limits, including deadlines to complete repairs and claim recoverable depreciation. TWIA claims must be filed within one year of the date of damage, subject to a possible extension of up to 180 days for good cause. Read your policy, and consult a Texas attorney about any deadline to file suit.
Should I stop repairs when hidden damage is found?
When it is safe and practical, pause long enough to photograph the damage and notify the insurer in writing before it is covered up. Many insurers want the chance to inspect. Continue any work needed to protect the property from further damage.
Can my contractor submit the supplement?
Contractors often provide documentation and invoices for supplements. Texas Insurance Code §4102.051 requires a license to act as a public adjuster, so a contractor who is not licensed as one generally should not negotiate the claim as your adjuster. You can also submit the supplement yourself.
Can a claim be supplemented after it was closed?
Often, yes, within the time allowed by the policy and applicable law. A closed claim can frequently be reopened when new damage is discovered or the original scope was incomplete.
How are public adjuster fees handled on a supplement?
Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. Ask how the contract treats payments made before you hired us.