
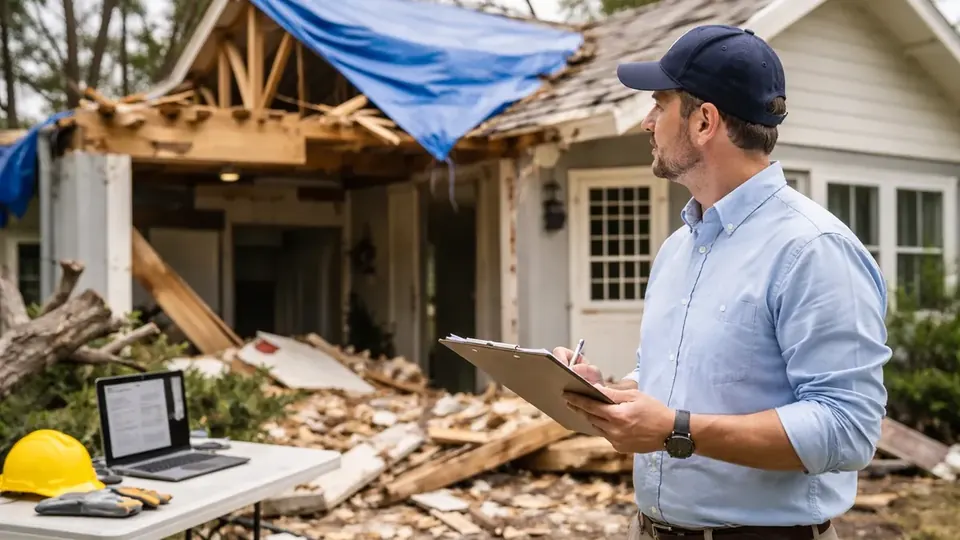
Corpus Christi hurricane damage claims are rarely simple. A single storm can tear off roofing, drive rain through walls and windows, push surge across the bays and barrier islands, and leave a property owner dealing with two or three insurers at once. If you own a home or business in Corpus Christi, Nueces County, or the surrounding Coastal Bend, this page explains how hurricane claims usually work, where disputes tend to start, and how a licensed public adjuster may help.
The Coastal Bend has a long hurricane record. Hurricane Celia came ashore near Aransas Pass on August 3, 1970 as a Category 4 storm (NWS Corpus Christi). Hurricane Harvey made landfall just east of Rockport on August 25, 2017, also at Category 4 (NHC Tropical Cyclone Report), and NOAA storm records describe storm tides of 6 to 8 feet in Port Aransas. Hurricane Hanna in 2020 and Tropical Storm Harold in 2023 were smaller, but both produced wind, rain, and elevated tides across the area. Our storm history page covers more of this record.
How Corpus Christi Hurricane Damage Claims Are Structured
Nueces, San Patricio, Aransas, and Kleberg counties all sit inside the Texas Windstorm Insurance Association (TWIA) catastrophe area. Because many private insurers exclude wind and hail near the coast, a typical Coastal Bend property owner may hold three separate policies after a hurricane:
| Policy | What it usually covers | Common hurricane issue |
|---|---|---|
| Homeowners or commercial property policy | Fire, theft, some water damage, and other named perils; often excludes wind and hail near the coast | Insurer says the loss belongs under the wind or flood policy |
| TWIA windstorm policy | Wind and hail only, for eligible properties in the catastrophe area | Disputes over whether damage came from wind or from water |
| NFIP or private flood policy | Rising water, including storm surge, subject to policy terms and limits | Surge damage mixed with wind damage on the same structure |
Each policy has its own deductible, its own deadlines, and its own adjuster. That is where many hurricane claims start to go sideways. For a deeper look at the TWIA side, see our TWIA windstorm claims page.
Wind vs. Water: The Most Common Hurricane Dispute
When a home on Padre Island, in Rockport, or along Ocean Drive takes both wind and surge, the wind insurer and the flood insurer may each point to the other. A wall that failed under wind pressure and then flooded can look, after the fact, like a flood-only loss. Interior water stains can come from wind-driven rain through a damaged roof or from rising water. Separating the two is detailed work.
Evidence that often helps includes:
- Water lines and debris lines inside and outside the building, measured and photographed.
- Roof and opening damage that shows how rain got in from above.
- Tide and surge records from NOAA stations such as Packery Channel, Port Aransas, or Rockport, plus NWS storm reports.
- Timeline evidence, such as when wind peaked compared with when water arrived.
Our article on wind vs. storm surge damage claims goes into this in more depth, and the flood damage claims page covers the flood policy side.
What Hurricane Damage Often Looks Like on the Coastal Bend
Construction around Corpus Christi shapes how hurricane damage appears. Slab-on-grade homes with composition shingles are common on the mainland, metal roofs are popular in rural Nueces and San Patricio counties, and many island homes are elevated. Damage we often see documented includes:
- Missing, creased, or lifted shingles and displaced ridge caps; see roof damage insurance claims.
- Wind-driven rain entering through soffits, vents, window frames, and stucco or brick veneer.
- Broken windows, garage doors pushed in, and damaged fences, carports, and outbuildings.
- Interior ceiling, insulation, drywall, and flooring damage after the roof was opened up.
- Surge damage to lower levels, breakaway walls, and equipment on elevated homes.
- Follow-on problems such as mold growth when drying was delayed.
Deductibles, Depreciation, and Code Upgrades
Several policy features control what a hurricane claim actually pays:
- Named-storm or wind/hail deductibles. Often a percentage of the dwelling limit. Read more in named-storm and hurricane deductibles in Texas.
- ACV vs. RCV. Under replacement cost coverage, the insurer typically pays actual cash value first and releases recoverable depreciation after repairs, within the time the policy allows.
- Ordinance or law coverage. The City of Corpus Christi adopted the 2021 International Residential Code with local amendments effective August 1, 2023, and re-roofing requires a permit. Code-required upgrades are only paid if your policy includes ordinance or law coverage, up to its limit. See local building codes.
- Windstorm certification. Repairs in the catastrophe area may need TDI windstorm inspection to keep the property eligible for TWIA coverage.
Living Expenses, Contents, and Business Income
The building is only one part of a hurricane claim. If a home is unlivable, many homeowners policies include loss of use or additional living expense coverage for reasonable extra costs such as a rental or hotel, subject to limits and policy terms. Contents claims need a room-by-room inventory with descriptions, ages, and replacement prices. Business owners may also have business income or extra expense coverage, which usually requires financial records showing what the shutdown cost. Each of these pieces is easy to overlook while the focus is on the roof. Our commercial property claims page covers the business side.
How a Corpus Christi Public Adjuster May Help
As a Corpus Christi Public Adjuster, we represent the policyholder, not the insurance company. On a hurricane claim, that work may include reviewing each policy, inspecting the property, separating wind damage from water damage as far as the evidence allows, preparing a detailed line-item estimate (often in Xactimate), gathering weather and tide records, and handling communication with each insurer's adjuster. If a claim has already been paid low, we can look at whether an insurance claim supplement or appraisal may fit.
We cannot promise a result. Outcomes depend on your policies and the facts of the loss. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.
Steps to Take After a Hurricane
- Stay safe first. Wait for local officials to clear your area before returning.
- Photograph and video everything before cleanup, including water lines and roof damage.
- Report the loss to every insurer that may be involved: homeowners, TWIA, and flood.
- Prevent further damage with tarps, board-up, and water removal, and keep the receipts.
- Keep a claim log of every call, email, inspection, and payment.
- Watch your deadlines. TWIA claims have statutory deadlines, and other policies set their own. Our claim deadline calculator can help you track them.
Hurricane claims are long and detailed, and many owners are also dealing with temporary housing, contractors, and lost business income at the same time. A Corpus Christi Public Adjuster can take on the claim paperwork so you can focus on getting the property back in shape. If you have questions about a lawsuit, bad faith, or the deadline to sue, consult a Texas attorney.
Frequently Asked Questions
Which policy pays for hurricane damage in Corpus Christi?
Often more than one. Many coastal homeowners carry a homeowners policy that excludes wind and hail, a TWIA windstorm policy for wind and hail, and a separate NFIP or private flood policy for rising water and storm surge. Which policy responds depends on what caused each part of the damage.
What is a named-storm or hurricane deductible?
Many Texas policies carry a separate wind/hail or named-storm deductible, often a percentage of the dwelling (Coverage A) limit rather than a flat dollar amount. Your declarations page shows the figure. Our hurricane deductible calculator can help you estimate it.
How long do I have to file a TWIA hurricane claim?
Under Texas Insurance Code Chapter 2210, a TWIA claim must be filed no later than one year after the date the damage occurs, with a possible extension of up to 180 days for good cause. Other policies have their own notice requirements, so report each claim promptly. For questions about deadlines to sue, consult a Texas attorney.
Does my homeowners policy cover storm surge?
Generally no. Standard homeowners and commercial property policies usually exclude flood, and storm surge is typically treated as flood. Surge damage is usually a matter for an NFIP or private flood policy, if you have one.
Should I make repairs before the adjuster inspects?
Make reasonable emergency repairs to prevent further damage, such as tarping a roof or boarding windows, and keep the receipts. Photograph everything first. Hold off on permanent repairs until the damage has been documented and the insurer has had a chance to inspect, unless waiting would cause more harm.
Can a public adjuster guarantee a larger hurricane settlement?
No. A public adjuster can help document the loss, prepare an estimate, and present the claim, but no one can guarantee an outcome. Results depend on the policy language and the facts of the loss.